

Why claims leaders want AI to automate tasks, not decisions | Insurance Business
Why claims leaders want AI to automate tasks, not decisions
Clayton Matthews on catastrophe claims, adjuster training and the fraud AI can’t yet stop
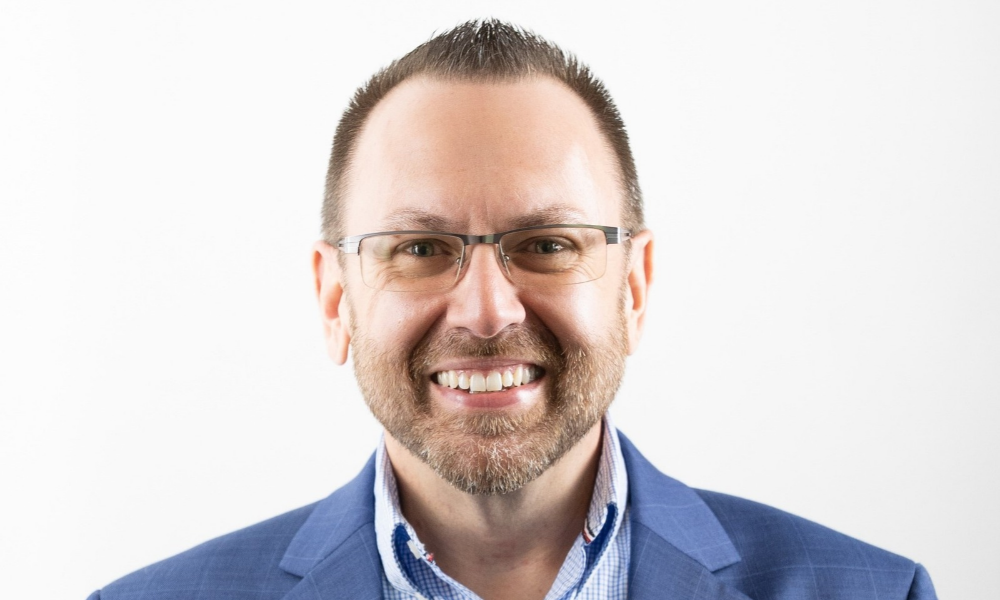
Claims departments are not struggling with workload right now, they are struggling with visibility, ownership and prioritization, according to Clayton Matthews (pictured), director of claims at Georgia-based Oakbridge Insurance. After three decades in P&C claims leadership, Matthews said the financial condition of the insurance market has improved even as the operational strain on adjusters has compounded, layering catastrophe volume, staffing turnover, litigation costs and new technology on top of one another at the same time.
Catastrophe claims test specialization, not headcount
Matthews said the biggest mistake claims leaders can make during a catastrophe is treating every claim tied to the event as a catastrophe claim. A roof leak or water damage behind a door happens with or without a hurricane on the map, he said, and the carriers pulling ahead are the ones being deliberate about who handles what.
“The carriers getting smarter are the ones being very deliberate about specialization – who does what, and which parts of technology can assist – so that we can create better touchpoints with customers,” Matthews said. “That’s probably the biggest hurdle right now: customers don’t feel like the communication is where it needs to be.”
Matthews said roughly 72% of the advocacy requests his team fields are communication-related, not disputes over the substance of a claim. Improving the first notice of loss (FNOL) process, he said, is where carriers can move the needle fastest, using artificial intelligence within strict guardrails and human spot-checking to get routine claims moving faster while reserving experienced adjusters for complex losses. That effort tracks with broader industry data: the JD Power 2026 U.S. Property Claims Satisfaction Study found overall claims satisfaction climbed even as repair and payment cycle times fell, pointing to digital investment paying off across the sector.
AI cuts routine work, but frays the training pipeline
Matthews described his approach to AI in one sentence: automate the transaction, augment the decision. Claims, he said, is “the perfect sandbox” for automation given its volume and rules-driven structure, but he pushed back on the idea that AI output should be treated as authoritative by newer staff.
“What happens when an AI tool gives what appears to be a mostly right answer – and a young adjuster takes it as gospel because it sounds authoritative? That concerns me deeply,” Matthews said.
The tension echoes concerns about AI weakening the claims talent pipeline that have circulated across the industry as automation absorbs entry-level, transactional work once used to train junior adjusters. Still, Matthews argued the shift may not gut the talent pool as some fear, since AI is freeing experienced adjusters from back-office work and allowing them to specialize further rather than eliminating their roles outright.
Fraud detection becomes an arms race
Fraud itself has not changed in kind, Matthews said invoice manipulation and identity fraud predate AI. What has changed is the cost of entry and the volume of contested claims. Where a policyholder once sent a short paragraph disputing a decision, Matthews said adjusters are now fielding AI-generated, 14-page demand letters that cannot be dismissed outright, since a single line within them may trigger coverage.
“We’re going to need tools to help us battle those tools,” Matthews said. “I think we’re heading toward a world that looks like BattleBots my agent that I’ve built against your agent that you’ve built. Whoever has the best knowledge and the best product wins.”
That framing lines up with warnings that AI-fueled fraud is forcing insurers into an arms race, as fraud-analytics executives describe a “perfect storm” of accessible generative tools and shifting consumer attitudes toward fraud. Matthews said his deeper concern sits beyond invoice fraud, with credentialed bad actors who gain legitimate system access and operate inside the ecosystem undetected by conventional red flags.
Ownership over process, after three decades in claims
Asked what he has changed his mind about, Matthews said he once equated control with process – the more checkpoints and file reviews, the better the claims management. He now believes the better model is clear ownership: giving adjusters financial authority to make decisions, then coaching rather than second-guessing them afterward.
“Don’t automate a disaster faster,” Matthews said. “If it’s a bad process, why would you speed it into automation? You need to stop first and examine your process before putting it into overdrive.”
That principle increasingly shapes how carriers are using AI as an evidence-gathering tool rather than an autonomous decision-maker, assembling policy terms, loss history and repair estimates faster while leaving judgment calls with adjusters. Matthews explained that the unresolved piece is still human: no chat tool has yet told him how to tell a policyholder, “I’m sorry.”
