


- Rockwell Automation announced it has joined Anthropic’s Project Glasswing, giving its security teams controlled access to Claude Mythos 5 to improve vulnerability discovery, validation, prioritization, and remediation across the industrial software and connected systems manufacturers depend on.
- This collaboration could deepen Rockwell Automation’s cybersecurity capabilities in critical infrastructure, reinforcing its role as a trusted automation partner for clients facing rising digital and operational risk across modern factories.
- We will examine how Rockwell Automation’s investment narrative around industrial automation and digital resilience is influenced by its Project Glasswing participation.
Scan how Rockwell Automation’s move into AI powered cyber defense compares with other industrial players by reviewing the hand picked 38 robotics and automation stocks shaping connected manufacturing security.
Rockwell Automation Investment Narrative Recap
To hold Rockwell Automation, you need to believe in long run demand for industrial automation, software and connected services that can support recurring revenue and high returns on capital. The short term swing factor still looks tied to customer CapEx timing, especially for longer cycle projects where delays can slow orders and push out services revenue.
The Project Glasswing news matters operationally but probably does not change that near term catalyst. It nudges the story toward stronger cybersecurity offerings rather than resetting expectations. The bigger risk remains heavy investment and higher debt being put to work just as tax headwinds and cautious industrial spending can pressure margins.
The clearest link to Rockwell Automation’s Glasswing move is its recent launch of TechConnectIQ Support, which already mixes AI tools with technical expertise to cut downtime and address factory skill gaps. Glasswing access to Claude Mythos 5 now feeds into the same automation plus software plus services pitch, only with deeper focus on cyber defense.
For you as a shareholder, the interest is whether TechConnectIQ and Project Glasswing together keep Software & Control and Lifecycle Services attractive, even if hardware demand softens or CapEx stays slow. Execution risk does not disappear, especially with high P/E and debt, but progress in AI enabled support and security could help sustain the existing earnings profile.
Rockwell Automation’s current earnings are about US$1.1b, and analysts expect that figure to reach roughly US$1.8b by 2029. This implies an earnings increase of about US$0.7b alongside forecast revenue of US$10.3b in the same year, supported by an assumed 5.5% annual revenue growth rate over the next few years.
Uncover why Rockwell Automation’s fair value indicates a 13% potential upside to its current price, a discount that may not last much longer.
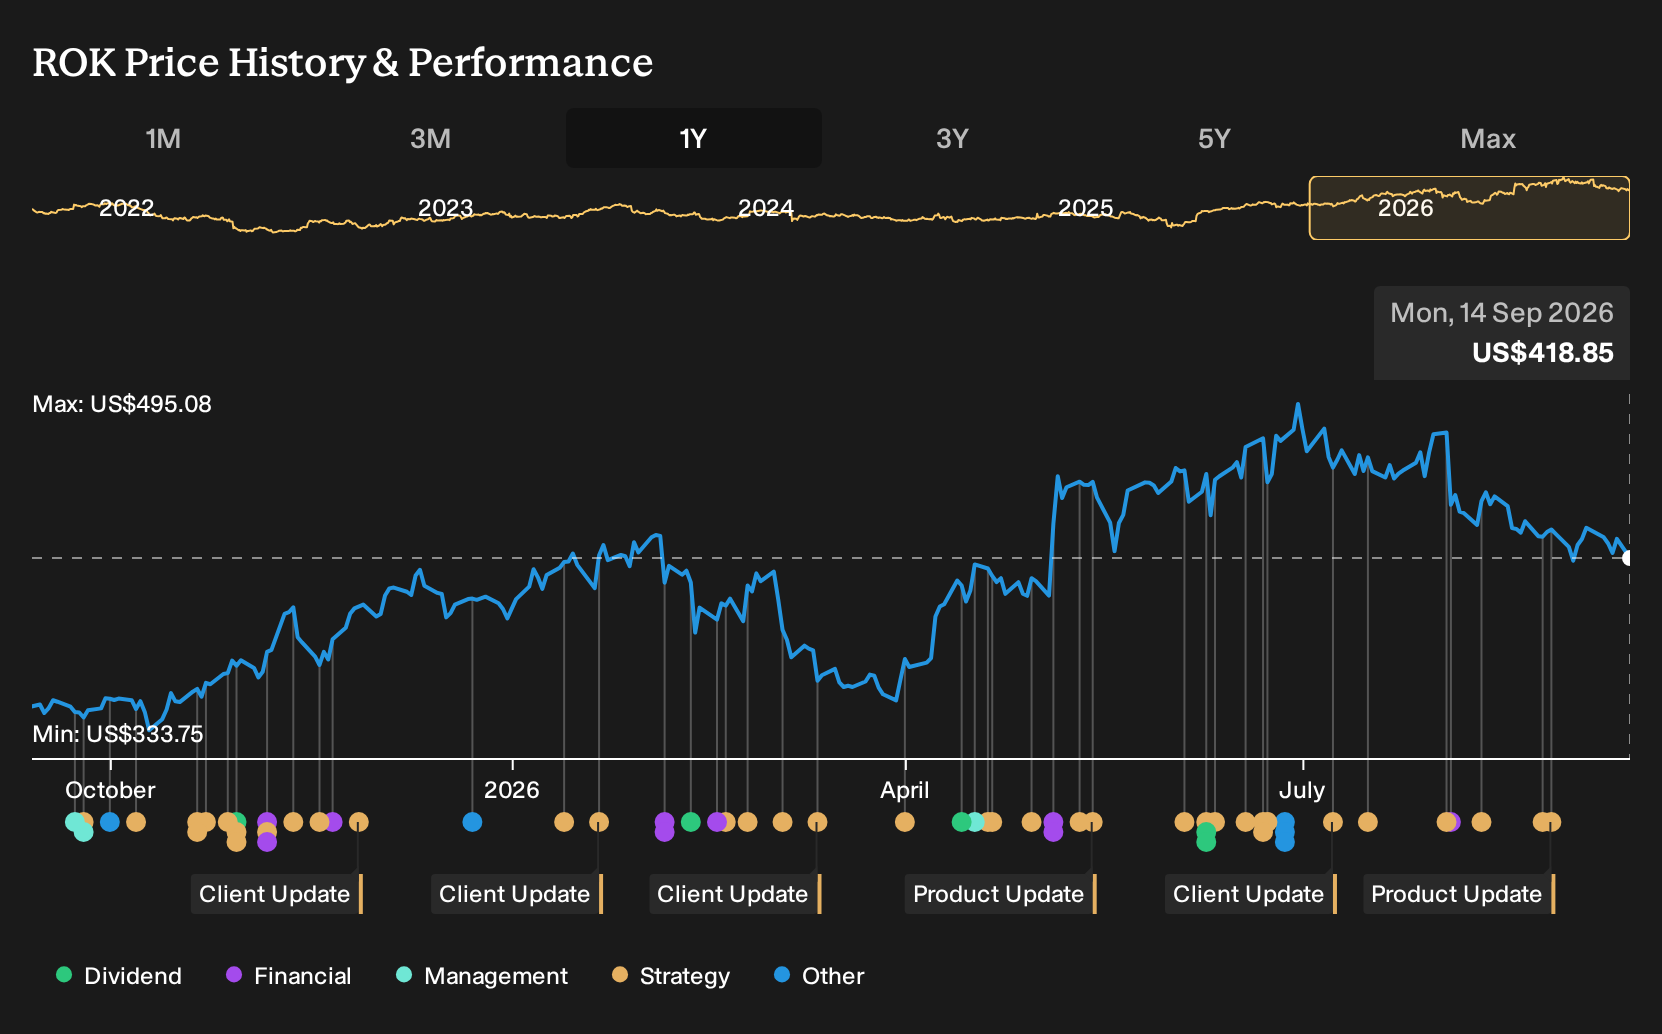
Exploring Other Perspectives
Alternative views on Rockwell Automation lean heavily on cybersecurity as a revenue catalyst rather than just a cost of doing business. The most optimistic analysts were already assuming 7.5% annual sales growth to about US$10.9b and US$2.1b in earnings by 2029. Those forecasts came before Project Glasswing, so opinions may shift meaningfully from here.
Explore 2 other Rockwell Automation fair value estimates, including one that suggests potential upside of up to 13% from the current price.
Decide For Yourself
Don’t just follow the ticker. Dig into the data and build a conviction that’s truly your own.
- A great starting point for your Rockwell Automation research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Rockwell Automation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rockwell Automation’s overall financial health at a glance.
Looking for more Rockwell Automation style investment ideas?
If the Rockwell Automation story has you thinking about what else might fit your watchlist, cast the net wider with the Simply Wall St Screener and compare businesses with different risk and income profiles.
- For investors who want income to feel sturdier through market swings, start with a set of potential 6 dividend fortresses that focus on higher yields with an emphasis on staying power.
- If capital preservation is front of mind, narrow your search to a 11 resilient stocks with low risk scores to see which businesses score well on balance sheet strength and volatility.
- For those hunting for future standouts before they are widely followed, review a 15 high quality undiscovered gems that combine solid fundamentals with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
New:AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly.Alternatively, email editorial-team@simplywallst.com
Oil routes are being dismantled one by one. The durable winner could be the North American energy left standing.
The durable premium you describe does not really exist for crude in a liquid market. This scenario, in almost a similar form, is happening thrice this year.
Persistent volatility raises the hurdle rate on every long-lived energy investment, which suppresses the supply response that would eventually fix the problem. The instability is self-perpetuating in a way the price level is not.

Are social media stocks the new Big Tobacco?
Greater regulatory scrutiny is catching up with digital platforms, posing a rising risk for social media stocks. But as Big Tobacco discovered, that’s not always a bad outcome for shareholders.
14
Sep 11, 2026
About NYSE:ROK
Rockwell Automation
Provides industrial automation and digital transformation solutions in North America, Europe, the Middle East, Africa, the Asia Pacific, and Latin America.
Solid track record with adequate balance sheet and pays a dividend.
Similar Companies
Market Insights
Are social media stocks the new Big Tobacco?AN
Andrew Legget
What 13F filings won’t tell you about a billionaire’s stock picksMI
Mitchell Lawler
Great earnings season, but are the earnings real?AN
Andrew Legget
Advertisement
Weekly Picks

Ceazaron Sparc AI·20 days ago
When GPS fails: this small cap is fixing a $54B drone problem
Fair Value:CA$5.2539.8% undervalued
194followersusers have followed this narrative
·0commentsusers have commented on this narrative
·29likesusers have liked this narrative
CO

composite32on Archrock·7 days ago
AI Needs Power. Power Needs Gas. Gas Needs Compression: The Archrock Investment Thesis
Fair Value:US$44.8832.1% undervalued
3followersusers have followed this narrative
·0commentsusers have commented on this narrative
·1likeusers have liked this narrative
JO

John_Ericon Advanced Energy Industries·16 days ago
AEIS Is Firing on Every Cylinder. My Problem Is the Safety Factor.

isidrohgon Lam Research·5 days ago
The Memory Shortage Is Lam’s Order Book
RecentlyUpdated Narratives

FRAGMENTSon SITE Centers·about 6 hours ago
SITE Centers Trades Around $2.90. It Had $238.9 Million of Cash. One $129.6 Million Decision Changes the Outcome.

waioaon UUE Holdings Berhad·about 7 hours ago
UUE Holdings Expands Into High-Voltage Power Infrastructure Through Strategic JV

RockeTelleron Honey Badger Silver·about 14 hours ago
Honey Badger: 766g/t AgEq, 5km of Tunnels, Mill Already There, Why September’s PEA Matters
Popular Narratives

AnalystConsensusTargeton NVIDIA·about 2 months ago
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8330.3% undervalued
1449followersusers have followed this narrative
·8commentsusers have commented on this narrative
·35likesusers have liked this narrative
AN

AnalystConsensusTargeton Alphabet·4 months ago
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures

AnalystConsensusTargeton Amazon.com·about 1 month ago
