


Amkor Technology (AMKR) just posted third quarter 2026 results, reporting sales of about US$2.0b and net income of US$190.6m, along with fresh guidance and a recently completed share repurchase tranche.
Despite the solid third quarter headline numbers and fresh buyback activity, Amkor Technology’s share price has swung sharply lower. It has fallen 14.5% on the day, 26.0% over the past week and 42.9% across 30 days, as investors digest new guidance, a trimmed fair value estimate of US$66.00 and mixed sentiment around capital spending and Communications exposure. This comes even though total shareholder return over three and five years remains positive at 39.4% and 41.2% respectively.
Spot opportunities that echo Amkor Technology’s mix of earnings power and volatility by scanning our hand picked 42 high quality undervalued stocks with solid cash generation and balance sheets.
Amkor Technology is producing healthy profits and investing heavily in advanced packaging, yet the share price has almost halved in a month. Are investors now underestimating the business, or correctly marking down the valuation?
Most Popular Narrative: 54% Undervalued
The most followed narrative pegs Amkor Technology’s fair value at $66.00, well above the last close at $30.49. As a result, the recent selloff sits against a valuation gap built on AI packaging and long term capacity plans.
Acceleration in AI data center and high performance computing programs, including HDFO CPU ramps and multiple 2.5D and high density fan out engagements, is increasing demand for advanced packaging. This can support higher revenue and a richer mix that benefits gross margin and earnings.
See why 24 investors see Amkor Technology as 54% undervalued.
The narrative relies on a 12.54% discount rate and assumes Amkor Technology can support $10.2b in future annual revenue with an 8.25% profit margin. These inputs feed into the $66.00 fair value estimate. That view also leans on a future P/E of 27.78x, compared with a much lower multiple implied by the current share price after the recent decline.
Result: Fair Value of $66.00 (UNDERVALUED)
Still, heavy capital commitments in Arizona and other regions, along with ongoing Communications softness, could erode margins and challenge the bullish Amkor Technology narrative.
Find out about the key risks to this Amkor Technology narrative.
Another View: Cash Flows Paint A Harsher Picture
While the popular Amkor Technology narrative leans on earnings and a $66.00 fair value, the SWS DCF model points in the opposite direction. On that cash flow view, AMKR at $30.49 trades well above an estimated value of $4.32, which suggests far less potential upside and significantly more valuation risk. Which version of reality do you trust when the numbers clash this sharply?
Look into how the SWS DCF model arrives at its fair value.
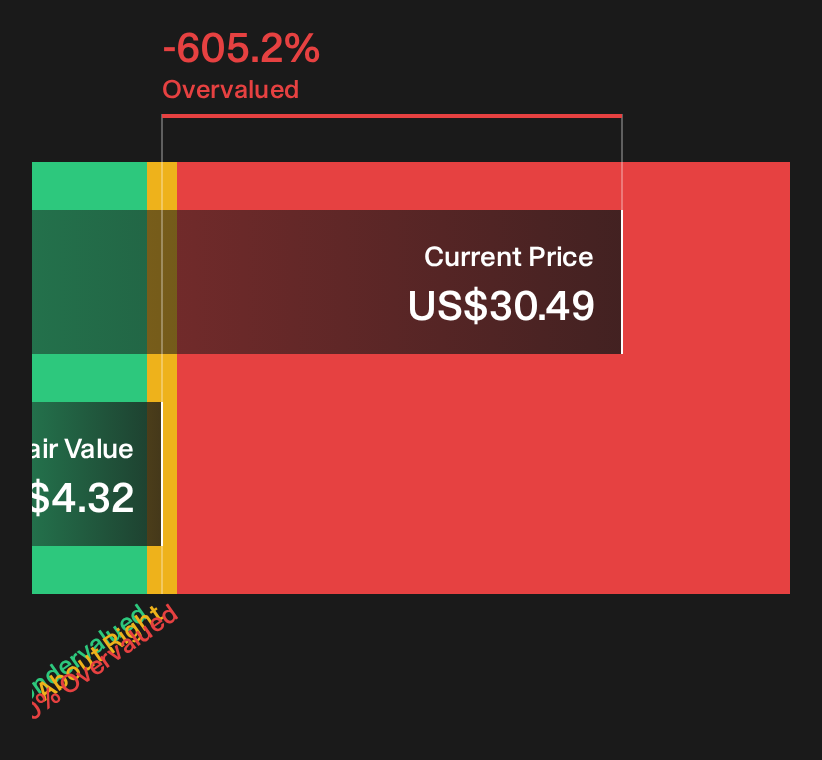
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Amkor Technology for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match – so you never miss a potential opportunity.
Next Steps
Big reactions like this often spark strong opinions, yet the real edge comes from acting quickly and testing the facts yourself against both the upside and the downside case. Start with the 4 key rewards and 2 important warning signs.
Hunting For More Ideas Beyond Amkor Technology?
Do not stop with one volatile chart. Use the Simply Wall St Screener to quickly surface fresh ideas that fit the kind of portfolio you actually want to build.
- Target resilient compounding by scanning a 32 resilient stocks with low risk scores that prioritises balance sheet strength and lower risk profiles.
- Chase value opportunities by reviewing a 21 high quality undiscovered gems built around strong fundamentals that fewer investors are watching closely.
- Reinforce income potential through a 6 dividend fortresses focused on companies offering higher yields with supporting financials.
New:Manage All Your Stock Portfolios in One Place
We’ve created the ultimate portfolio companion for stock investors, and it’s free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks
Have feedback on this article? Concerned about the content? Get in touch with us directly.Alternatively, email editorial-team@simplywallst.com
Weekly Picks

Ceazaron Buffalo Potash·11 days ago
Under the radar: This $78M stock controls a $1.5B project and it’ll start producing in a few months
Fair Value:CA$1.0630.2% undervalued
138followersusers have followed this narrative
·3commentsusers have commented on this narrative
·27likesusers have liked this narrative
JO

John_Ericon Microsoft·5 days ago
Microsoft (MSFT): The AI Bull Case Everyone Sees, Trading at a Multiple Nobody’s Willing to Pay
Fair Value:US$60010.7% undervalued
57followersusers have followed this narrative
·4commentsusers have commented on this narrative
·10likesusers have liked this narrative
MA

MarkoVTon Alphabet·8 days ago
Mo’ Money, Mo’ Problems

Michael_Jayon TOYO·about 1 month ago
TOYO May Be The Most Undervalued Company In The Market Today. Here’s Why:
Fair Value:US$18.473.0% undervalued
47followersusers have followed this narrative
·3commentsusers have commented on this narrative
·18likesusers have liked this narrative
M
mitchell_lawler
The Foxhole
Backlash against data centers is proving to be a risk for AI. What if it’s the ignition for SpaceX?
913
Mitch Lawler
Market Insights
What does rising cash burn mean for AI stocks?
Alphabet had its worst day on record after reporting, and it wasn’t alone. After three years of rewarding spending by AI stocks, the market has started to become wary of just how much that growth is really costing.
Sasha Jovanovic
Sasha is an Equity Analyst at Simply Wall St with 15 years financial markets experience. He is a CFA Charterholder and holds Bachelor degrees in Mathematics and International Studies from the University of Technology, Sydney, Australia. He worked at CommSec Investment Management as an Investment Analyst from 2014 and later at Sequoia Financial Group as a Portfolio Analyst from 2018.
About NasdaqGS:AMKR
Amkor Technology
Provides outsourced semiconductor packaging and test services in the United States, Japan, Europe, and the Asia Pacific.
Excellent balance sheet with proven track record.
Similar Companies
Market Insights
What does rising cash burn mean for AI stocks?MI
Mitch Lawler
What memory stocks can teach us about cyclesAN
Andrew Legget
AI has flipped the story on cybersecurity stocks, twiceMI
Mitch Lawler
Advertisement
RecentlyUpdated Narratives

StoxEuropeon Sipef·about 1 hour ago
Why I Invest in SIPEF?

tripledubon Sprouts Farmers Market·about 5 hours ago
The Grocery Store That Shrank Its Way to Prosperity

tripledubon NVIDIA·about 7 hours ago
NVIDIA Is the Best Business in America. That Doesn’t Mean You Should Buy It.
Fair Value:US$149.3221.6% overvalued
20followersusers have followed this narrative
·1commentusers have commented on this narrative
·0likesusers have liked this narrative
Popular Narratives
ANAnalystConsensusTargeton NVIDIA·22 days ago
AI Factory Demand And Physical AI Workloads Will Drive Multi‑Year Upside Potential
Fair Value:US$328.7244.8% undervalued
1719followersusers have followed this narrative
·8commentsusers have commented on this narrative
·37likesusers have liked this narrative
ANAnalystConsensusTargeton Microsoft·5 days ago
AI Infrastructure And Cloud Commitments Will Drive Long-Term Upside For This Business

AnalystConsensusTargeton Amazon.com·about 1 month ago
